
Body corporate records are useful, but they are not a perfect transcript of everything that has happened.
Minutes summarise meetings. Correspondence captures what was put in writing. Financial statements show where money went, but not always why. Reports may sit separately from the minutes that refer to them.
Most gaps and inconsistencies are likely to be unintentional. They arise from ordinary administrative practices: brief minutes, informal discussions, inconsistent terminology, assumed background knowledge or decisions made outside formal meetings. A record can give a misleading impression without anyone intending that outcome.
Sometimes, however, information may be deliberately left out or softened.
Proving that intention from the records alone is difficult. The sounder approach is to identify the gap or inconsistency, explain its significance and avoid assuming why it occurred.
When reviewing records, it helps to ask both what they say and what further information would be needed to understand the issue. These ten patterns show why that matters.
1. Important discussions happen by email
Committee members may conduct substantial discussions by email. The minutes might record only a short outcome, such as “Quote approved”, while the correspondence contains weeks of debate about a defect, its urgency, competing quotes, funding concerns or disagreement about the proposed work.
The decision may be visible while the reasoning behind it is not. Where available, the relevant correspondence can help explain how the decision was reached and what concerns remained.
2. Issues are discussed but never formally recorded
Some matters are dealt with verbally. A committee member may speak with the body corporate manager, a contractor may explain a problem onsite, or owners may discuss it before or after a meeting. If those conversations are not documented, a later reader may see only fragments of the history.
An issue that appears suddenly in the records may not be new. It may simply be the first time it was formally documented. The first recorded reference establishes when it appears in the material reviewed, rather than necessarily when it began.
3. The wording softens what is happening
A significant problem may be described in neutral terms such as “maintenance issue”, “rectification”, “remedial works”, “building matter”, “contractor attendance” or “consultant review”. Those descriptions are not necessarily inaccurate, but they may convey little about the seriousness of the underlying issue.
Neutral wording can reflect routine summarising or uncertainty about the problem. It does not, by itself, establish an attempt to minimise it. Read the entry alongside related reports, correspondence and costs to understand its significance.
4. The label is avoided altogether
The financial effect of a decision may be apparent even though a familiar label never appears. For example, ordinary contributions may increase sharply for part of a financial year to meet an urgent funding need, rather than a separately identified special levy being raised.
Owners still face an increased financial burden, but a search for “special levy” may find nothing. This does not make the increased contributions a special levy or establish concealment. It means the reviewer needs to examine the amounts, timing and stated reasons for the increase, rather than rely on one search term.
5. The decision is recorded but the problem is not
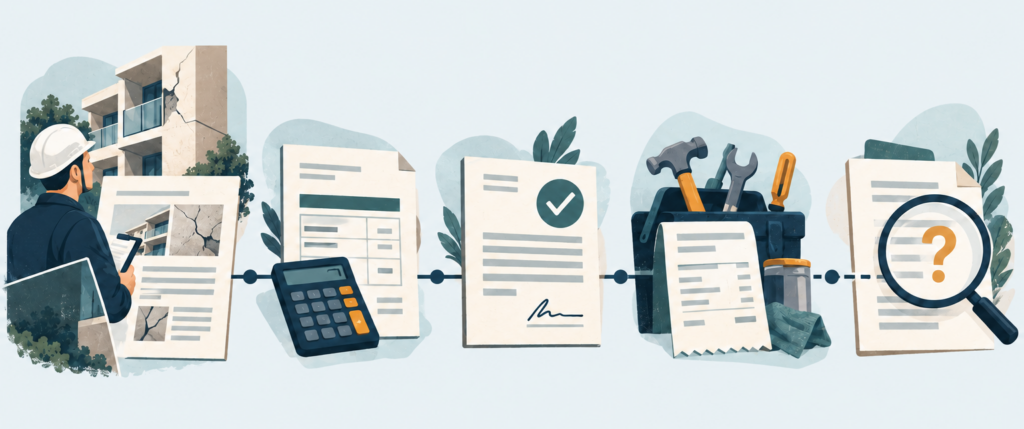
Minutes may record that the committee accepted a waterproofing quotation without explaining what was leaking, how long it had been occurring, whether a consultant was involved or whether earlier repairs had failed.
The decision can be clear while the problem that prompted it remains largely invisible. The quotation, scope of works and earlier correspondence may supply the missing background. Without them, the nature and extent of the problem may remain uncertain.
6. The problem is recorded but the outcome disappears
A report identifies a defect, quotes are obtained and the committee discusses the matter. Then the issue seems to vanish from later records. That does not necessarily mean it was resolved.
The work may have been completed without further discussion, the project may have stalled, or the issue may have been absorbed into another project or renamed. Review the sequence and look for evidence of completion and any later recurrence. If no outcome can be found, report that limitation rather than treating silence as proof of resolution.
7. The same issue appears under different names
Long-running problems may change terminology as they progress. “Water ingress” might later appear as “balcony waterproofing”, “consultant investigation”, “façade rectification” or an “insurance claim”.
Treating every reference as a separate matter can fragment the history. Dates, locations, contractors and report references can help establish whether entries belong to the same thread. Similar wording alone is not enough to assume a connection; where the link is uncertain, that uncertainty should remain visible.
8. The important information is somewhere else
A brief minute entry such as “Engineer’s report received” may sit beside a report containing much more significant findings. The same applies to contractor reports, insurance assessments, legal correspondence, scopes of works, quotations and building inspections.
A reference to another document is a reason to look further. If the document is unavailable, its contents should not be inferred from the brief entry alone. Identify the missing document and explain what cannot be assessed without it.
9. Financial records show the consequence without the cause
Sometimes the first obvious sign of a problem is financial: a sudden contribution increase, an administrative fund deficit, substantial consultant costs, repeated legal expenses or a large repair invoice. An unexpected movement between funds may also warrant closer examination.
The financial records may show expenditure or a funding change without explaining the underlying issue. Trace the entry back to invoices, budgets, resolutions and related correspondence. A cost is a useful lead, but its amount or description alone may not establish what happened or why.
10. Sometimes information is deliberately left out
Most incomplete records are not evidence of manipulation. Sometimes, however, information is deliberately excluded or softened because participants are concerned about how a scheme may appear to prospective buyers.
I have attended meetings where participants discussed whether certain information should be excluded from the minutes because of concern about its effect on property values.
That is a first-hand observation of the discussion. It does not, by itself, establish that the proposed omission occurred, or that a particular set of records was manipulated. It illustrates that concern about resale can influence what participants want recorded.
Leaving information out does not remove the underlying problem; it can make the history harder for later owners, buyers and committees to understand. Even so, intention is difficult to prove from the records alone. A gap, softened wording or unexplained change should be identified for what it shows, without attributing a motive unless the evidence supports it.
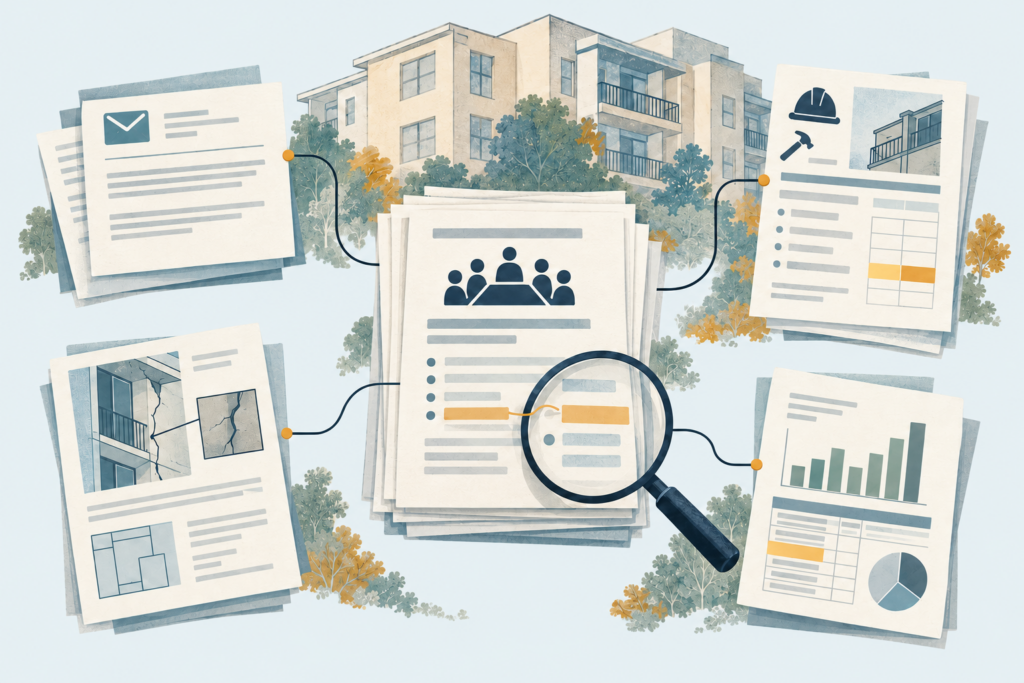
How to recognise an incomplete thread
There is rarely one definitive sign.
Look for sudden jumps in the story, decisions without background, reports referred to but unavailable, quotes without later evidence of works, unexplained financial movements, changing terminology or issues that disappear without a recorded outcome.
Later references to events missing from earlier records may also point to an incomplete history.
These patterns do not prove information has been deliberately hidden. They indicate where further documents or clarification may be needed.
Follow what should have happened next
Ask what you would expect to see next if an issue had progressed. If an engineer identified a defect, was a scope prepared? If quotes were obtained, was a contractor selected? If works were approved, were they funded and completed? If they were completed, did the problem recur? If ordinary contributions increased sharply, what funding need did the increase address?
An expected step that cannot be found is a question to investigate. It is not proof that the step never occurred. Distinguish between an event that did not happen and an event for which evidence was not found in the records reviewed.
Read the records with evidentiary discipline
Body corporate records remain a valuable source for understanding a scheme. A careful review connects related documents, follows the chronology and separates recorded facts from interpretation and unanswered questions.
For PPSR reporting, the principle is straightforward: identify missing or apparently curated information, describe the evidence and its limits, and do not overstate motive. For example, “No evidence of completion was found in the records reviewed” is more precise than “The work was never completed”.
Most misleading impressions arise from abbreviated, fragmented or imperfect records. Sometimes information is deliberately left out or softened. The reviewer’s task is to explain what the available evidence supports, what remains uncertain and what further information would help complete the picture.
Buying into a body corporate? A pre-purchase strata report can help connect the records, identify potential risks and understand remaining questions.
This article provides general information only. It is not legal, financial, engineering or building advice. The circumstances of every body corporate are different. Obtain advice from an appropriately qualified professional where necessary.